The Roth conversion optimizer that leaves your client the most.
How much to convert each year and when to claim Social Security. Built for financial advisors.
Your account and first calculation are free.
Every number is calculated from tax law. No AI.
An example client
Single, born 1965, Arizona. $2 million in a Traditional IRA and $48,000 a year of Social Security, with 6% returns and 3% inflation, through age 90.
OptiRoth’s plan compared with common conversion strategies
| Select a strategy to compare | After-tax value in 2055 |
|---|---|
| OptiRoth’s plan | $11,261,815 |
| $10,303,370 | |
| $9,727,699 | |
| $7,762,829 |
This is one client. See ten example plans for other situations, such as an early retiree, a couple near the IRMAA thresholds and a client who is still working.
+$958,445 more with OptiRoth’s plan by 2055 vs. converting $250,000 a year
| Year | OptiRoth’s plan | Convert $250,000 a year | Fill the 22% bracket every year | No conversions |
|---|---|---|---|---|
| 2026 | $1,333,002 | $1,333,002 | $1,333,002 | $1,333,002 |
| 2027 | $1,449,776 | $1,474,096 | $1,438,327 | $1,411,572 |
| 2028 | $1,568,549 | $1,619,534 | $1,546,836 | $1,493,274 |
| 2029 | $1,678,892 | $1,768,199 | $1,659,904 | $1,580,439 |
| 2030 | $1,821,474 | $1,910,630 | $1,773,019 | $1,668,990 |
| 2031 | $2,037,379 | $2,152,467 | $1,930,306 | $1,764,004 |
| 2032 | $2,223,426 | $2,342,277 | $2,070,781 | $1,864,650 |
| 2033 | $2,415,662 | $2,538,765 | $2,219,649 | $1,971,262 |
| 2034 | $2,628,943 | $2,734,689 | $2,377,409 | $2,084,199 |
| 2035 | $2,852,526 | $2,925,512 | $2,591,701 | $2,250,945 |
| 2036 | $3,085,744 | $3,135,557 | $2,817,366 | $2,446,580 |
| 2037 | $3,336,208 | $3,357,230 | $3,055,021 | $2,652,222 |
| 2038 | $3,607,427 | $3,591,189 | $3,305,294 | $2,868,387 |
| 2039 | $3,892,957 | $3,838,116 | $3,568,867 | $3,095,625 |
| 2040 | $4,193,117 | $4,098,762 | $3,846,450 | $3,334,520 |
| 2041 | $4,521,087 | $4,373,881 | $4,138,156 | $3,598,515 |
| 2042 | $4,859,657 | $4,664,309 | $4,442,411 | $3,864,753 |
| 2043 | $5,216,867 | $4,970,919 | $4,759,661 | $4,137,615 |
| 2044 | $5,597,511 | $5,294,620 | $5,090,469 | $4,416,862 |
| 2045 | $5,982,758 | $5,636,392 | $5,435,360 | $4,698,973 |
| 2046 | $6,393,758 | $5,997,265 | $5,794,718 | $4,986,696 |
| 2047 | $6,825,403 | $6,378,336 | $6,166,642 | $5,279,804 |
| 2048 | $7,280,589 | $6,780,762 | $6,553,802 | $5,578,051 |
| 2049 | $7,760,528 | $7,205,768 | $6,956,961 | $5,881,129 |
| 2050 | $8,267,321 | $7,654,488 | $7,375,978 | $6,188,695 |
| 2051 | $8,802,535 | $8,128,211 | $7,811,308 | $6,500,357 |
| 2052 | $9,367,805 | $8,628,393 | $8,263,543 | $6,811,919 |
| 2053 | $9,964,865 | $9,156,553 | $8,733,321 | $7,126,528 |
| 2054 | $10,595,554 | $9,714,308 | $9,221,259 | $7,443,674 |
| 2055 | $11,261,815 | $10,303,370 | $9,727,699 | $7,762,829 |
How it searches for the best plan
OptiRoth searches for the series of yearly conversions that leaves the most after-tax money over your client’s whole plan.
The panels below come from our sample plan, a different client from the example above.
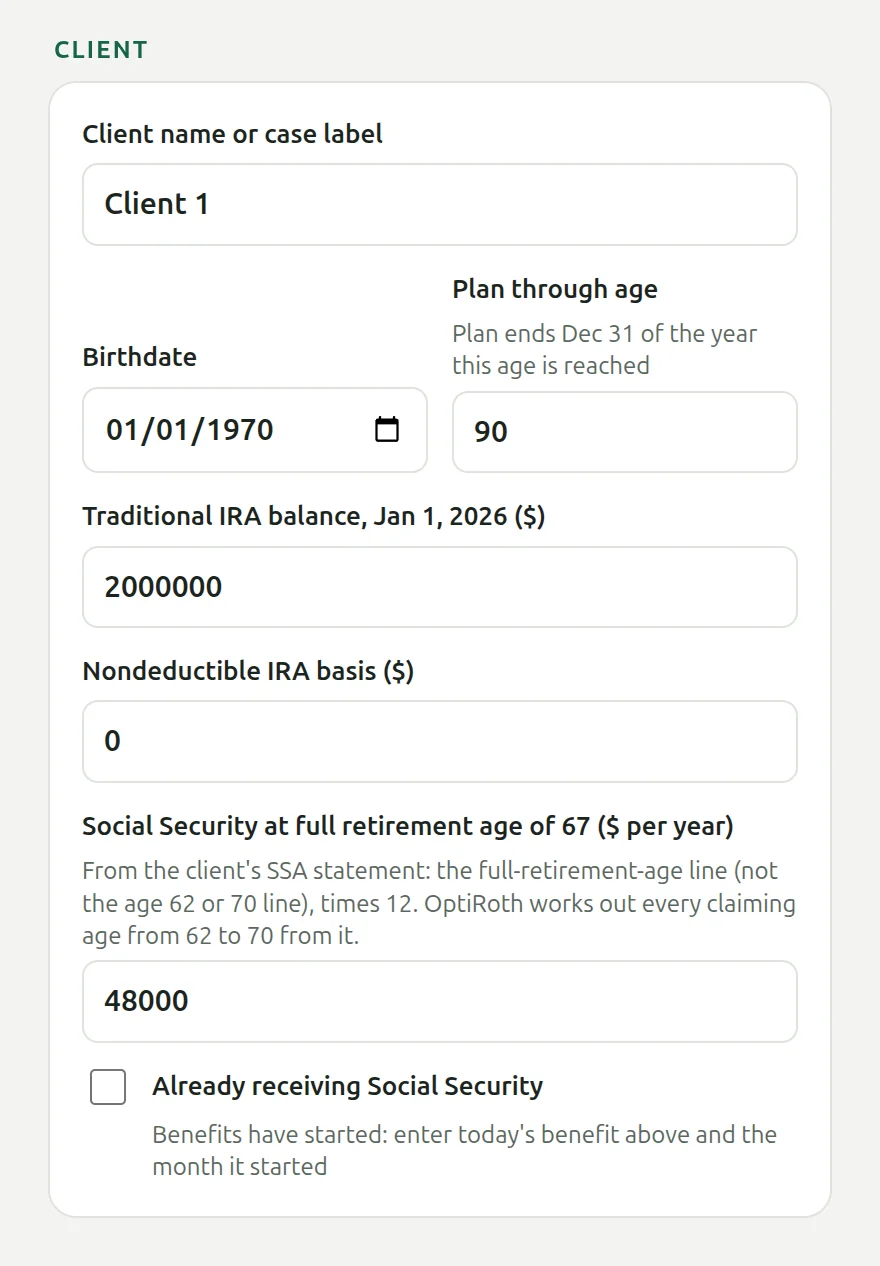
Enter your client’s details
Their ages, accounts, income and spending, plus your economic assumptions.
Client details
- Birthdate and plan-through age
- IRA and 401(k) balances, contributions and basis
- Social Security benefit, or the benefit already being paid
- Job income, pension and retirement date
- State of residence, cash balance and monthly living expenses
Economic assumptions
- Traditional, Roth and cash returns
- Inflation
- Social Security raises (COLA)
- Tax-bracket growth
Compare every claiming age
OptiRoth runs a full search at every claiming age from 62 to 70.
Social Security claiming choices compared
Every claiming age is calculated in full.
| Claiming age | After-tax value (highest result for this claiming age) | Compared with the highest result |
|---|---|---|
| Dec 2039 (age 70y 0m) | $2,807,407 | $0 |
| Nov 2039 (age 69y 11m) | $2,806,178 | −$1,229 |
| Dec 2038 (age 69y 0m) | $2,798,413 | −$8,994 |
| Dec 2037 (age 68y 0m) | $2,774,510 | −$32,897 |
| Dec 2036 (age 67y 0m) | $2,736,145 | −$71,262 |
| Dec 2035 (age 66y 0m) | $2,720,194 | −$87,213 |
| Dec 2034 (age 65y 0m) | $2,693,398 | −$114,008 |
| Dec 2033 (age 64y 0m) | $2,648,850 | −$158,557 |
| Dec 2032 (age 63y 0m) | $2,642,292 | −$165,115 |
| Jan 2032 (age 62y 1m) | $2,623,387 | −$184,020 |
Simulate every month
Each plan is run month by month: income, Social Security, withdrawals, Medicare premiums and account growth, with federal and state tax figured for each year.
Year-by-year plan
Three of the plan’s 35 years.
| Year | Age | Roth conversion | Required distribution (RMD) | All IRA withdrawals, including the RMD | Social Security | Job income | AGI | Federal tax | State tax | Other federal tax | Medicare premiums | Traditional IRA, year end | Roth IRA, year end | Cash, year end |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2029 | 59 | $94,516 | $0 | $131,523 | $0 | $0 | $226,039 | $42,567 | $5,245 | $3,958 | $0 | $1,861,521 | $158,614 | $0 |
| 2030 | 60 | $96,522 | $0 | $130,075 | $0 | $0 | $226,597 | $42,672 | $5,258 | $0 | $0 | $1,743,981 | $264,653 | $0 |
| 2031 | 61 | $94,499 | $0 | $132,658 | $0 | $0 | $227,157 | $42,777 | $5,271 | $0 | $0 | $1,618,750 | $375,031 | $0 |
Refine and verify
The leading plan’s conversion amounts are refined to the dollar, then rerun through the full month-by-month simulation.
Why each year’s amount
Two of the plan’s 35 years.
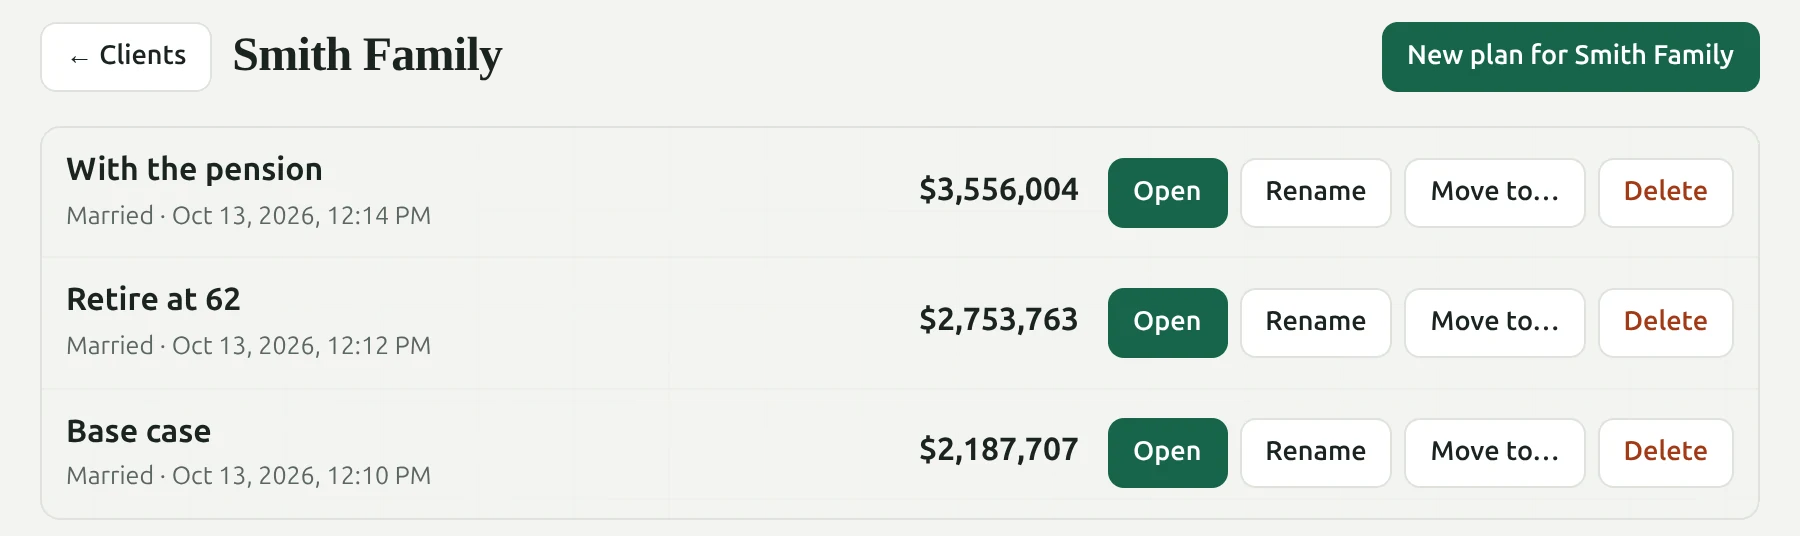
Organization for every client
Every plan is saved in your client’s folder, so you can reopen, compare or rerun it when your client’s situation changes.
What the simulation includes
The tax and account rules included in every plan.
Why OptiRoth explains how the engine uses them and how it compares with other Roth software.
- 01Federal tax
- 2026 brackets and deductions, and the IRS's 2027 brackets and deductions from 2027 on, including the extra deduction for people 65 and older (2025 through 2028).
- 02Social Security
- Taxation of benefits, spousal benefits, payroll tax, and the earnings test (benefits are withheld if your client works before full retirement age).
- 03Medicare
- Premiums, including income-related (IRMAA) surcharges based on income from two years earlier.
- 04Required minimum distributions
- Annual RMDs from your client’s RMD age, including deferring the first distribution to April 1 of the following year.
- 05Workplace plans
- Traditional and Roth 401(k)s: contributions, employer contributions, the yearly limits, and rolling into an IRA at retirement.
- 06Pensions
- Defined-benefit pensions, with their COLA and any tax-free part from after-tax contributions.
- 07Account rules
- IRA basis, the pro-rata rule, the 10% early-withdrawal penalty before age 59½, and the Roth 5-year rules.
- 08State tax
- All 50 states and DC: brackets, Social Security treatment, and retirement-income exclusions, including how each state treats a Roth conversion. Local taxes, like New York City’s, aren’t included.
- 09Return limits
- Returns are capped, and the Roth return can be at most 2 percentage points above the Traditional return, which keeps plans from relying on unrealistic returns.
Four levels of precision
Every level runs the same engine, tax rules and simulation. Higher levels search more finely, so they take longer and can find a better plan.
- UltrafastA quick first look.
- LowA fast, solid plan.
- MediumA closer look, down to the dollar.
- HighOur most precise plan. 5 per month, ready the next business day.
Pricing
Every subscription runs the same engine at every precision level.
Basic
- Unlimited Ultrafast, Low and Medium precision runs
- 5 High precision runs a month (our most precise)
- How much to convert each year
- When to claim Social Security
- The plan compared with no conversions
- Client folders and saved plans
Pro Recommended
Everything in Basic, plus
- Full year-by-year detail: taxes, Medicare premiums (including IRMAA), required minimum distributions and balances
- The reasoning behind every year’s amount
- A client-ready PDF report and a spreadsheet of every High precision plan
- Every Social Security claiming age compared
- Compare the plan with your own conversion amounts and save the comparisons
Pro for teams
Everything in Pro for each advisor, plus
- Choose how many advisors need licenses
- Invite each advisor by email, or send them a license code
- See each advisor’s activity and client plans, and reassign clients
- Client folders stay with your firm when an advisor leaves
- One bill: only the admin manages licenses, billing and cancellation
Your account is free, and so is your first calculation, which includes every Pro feature. After that, choose a subscription. Each saved plan keeps the level of detail of the subscription it was run under.
Prices exclude any applicable tax. Subscriptions renew automatically; cancel any time in your Profile.
OptiRoth is software for financial professionals. It does not give investment, tax or legal advice.
Questions advisors ask
Is OptiRoth tax or investment advice?
No. It’s a planning tool for financial professionals and recommends no investments. Results depend on your assumptions, and the advice you give is your own.
What is it trying to maximize?
The money your client has left after taxes at the end of the plan, counting IRA money after the tax it would owe when withdrawn.
Which states are supported?
All 50 states and DC, with up-to-date rules. Local taxes, like New York City’s, aren’t included, and the client is assumed to stay in one state.
Does it handle married couples and single clients?
Yes. For couples, OptiRoth tests both spouses’ Social Security claiming ages together.
Do I need an account?
Not for your first calculation: tick one box confirming you’re a professional and run it. An account is free and keeps every plan in a client folder; calculations run in the background and take minutes to hours, and we email you when a High precision plan is ready (the next business day). You can see a sample plan without an account.
Run your first client through OptiRoth
Your account and first calculation are free.